

Blogs
PW Consulting: Lignin Products Market Hits $729.42M in 2025, Projected 4.28% CAGR to $978.1M by 2032
By PW Consulting, 2026-09-16
Unlocking the Potential of Lignin: Strategic Insights for the 2026 Market Landscape
The global transition toward a bio-based economy is no longer a theoretical concept; it is a market reality reshaping supply chains, product formulations, and competitive dynamics across multiple industries. At the forefront of this shift is the lignin value chain. Often dismissed as a byproduct of the pulp and paper industry, lignin has emerged as a versatile, renewable alternative to petrochemical-derived materials. However, realizing its full commercial potential requires more than just technological innovation; it demands precise market intelligence to navigate a complex landscape of regulatory hurdles, fragmented supply sources, and evolving application requirements.
Lignin Products Market
PW Consulting is pleased to introduce our comprehensive market research report on the Lignin Products Market. This study is designed specifically for strategic decision-makers who need to allocate capital, identify partnership opportunities, and mitigate risk in the 2026-2032 forecast period. By combining rigorous quantitative analysis with qualitative competitive profiling, this report serves as an essential compass for navigating the next wave of industrial bioproducts.
Market Trajectory and Growth Catalysts
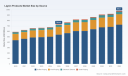
The lignin market has demonstrated steady resilience and growth over the past half-decade, driven by increasing demand for sustainable industrial inputs. Our analysis tracks the market value from 2020 through the base year of 2025, projecting a continued upward trend into the next decade. In 2020, the global market was valued at approximately 591 million USD. By 2025, this figure has risen to an estimated 729 million USD, reflecting a consistent trajectory of adoption across key end-user sectors.
Looking ahead, the strategic opportunity lies in the forecasted growth window. The market is expected to expand from its 2026 starting point of roughly 767 million USD to nearly 978 million USD by 2032. This projection implies a Compound Annual Growth Rate (CAGR) of 4.28 percent over the forecast period. While this growth rate may appear moderate at first glance, it is essential to contextualize it within the broader chemical industry, where volume growth for traditional bulk chemicals often lags behind specialty bioproducts. The steady CAGR indicates a maturing market that is transitioning from niche experimentation to mainstream commercial viability.
Several underlying drivers are fueling this expansion. First, the regulatory push toward carbon reduction and the circular economy is compelling industries to seek renewable feedstocks. Lignin, as the second most abundant biopolymer on Earth, offers a scalable solution for replacing fossil-based phenols, polyols, and dispersants. Second, technological advancements in separation and purification processes are lowering the cost barrier, making lignin-derived products more competitive against incumbent synthetic alternatives. Third, specific application sectors, such as agriculture and construction, are increasingly recognizing the functional benefits of lignin-based additives, ranging from improved feed efficiency to enhanced concrete setting properties.
Competitive Landscape and Strategic Positioning
Understanding the competitive dynamics is critical for any firm looking to enter or expand within this market. The lignin value chain is characterized by a mix of established pulp and paper giants leveraging their existing biomass access and specialized players focusing on high-value application development. Our report provides a detailed profiling of key market participants who are defining the standard for quality and innovation.
In Northern Europe, companies like Borregaard LignoTech and Domsjö Fabriker represent the legacy strength of the sulfite pulping industry. These organizations have long mastered the extraction and refinement of lignosulfonates. Borregaard, headquartered in Sarpsborg, Norway, continues to lead in specialized biopolymers and lignosulfonates, particularly within agriculture for animal feed binders and organic amendments. Their recent regulatory re-authorization for use in animal feed within the EU in February 2024 underscores the importance of compliance in maintaining market access. Similarly, Domsjö Fabriker in Sweden focuses on sulfite lignin products for agricultural and construction uses, leveraging local infrastructure to secure feedstock continuity.
Finnish competitors are also aggressively positioning themselves through differentiation. UPM Biochemicals has carved a niche in lignin-derived renewable functional fillers. Their collaboration with Nokian Tyres to introduce a concept tire using UPM BioMotion Renewable Functional Fillers highlights the potential for lignin to penetrate high-performance rubber applications. Meanwhile, Stora Enso produces kraft lignin products aimed at wood panel resins and feed binders, utilizing their extensive forestry resources to secure a loyal downstream customer base.
In the Netherlands, LignoStar International B.V. operates as a specialized marketer and seller, focusing on calcium lignosulfonates for animal feed pellet binders and organic amendments. This business model emphasizes distribution agility and technical service support rather than heavy vertical integration. Conversely, the Asian market is seeing the rise of integrated agro-chemical players. Green Agrochem, based in Beijing, operates divisions focused on lignin and lignosulfonates for fertilizer binders, pesticide dispersants, and animal feed applications. Their recent release of technical data sheets for magnesium lignosulfonate in June 2025 demonstrates a focus on product specification and market promotion to capture industrial and agricultural demand.
A critical element of our competitive analysis involves assessing market concentration. The report details the market share distribution among the top players, revealing the level of consolidation and the bargaining power held by key suppliers. This data is vital for understanding pricing dynamics and supply security risks.
Segmentation Analysis: Sources, Products, and Applications
To truly grasp where value is created, one must dissect the market along multiple dimensions. Our report segments the market by source, product type, application, and region, providing a granular view of revenue contributions without relying on broad generalizations.
By Source: The supply of lignin is intrinsically linked to pulping processes. The report quantifies the revenue contribution from Sulfite Pulping, Kraft Pulping, Cellulosic Ethanol, and Soda Pulping. Each source yields lignin with distinct chemical properties and impurity profiles, which in turn dictates suitability for specific downstream applications. For instance, sulfite-derived lignosulfonates are historically dominant in dispersant and binder applications, while kraft lignin is gaining traction in resin formulations and carbon fiber precursors. The analysis highlights which source types are driving revenue growth and where future capacity investments are likely to concentrate.
By Product: The product landscape is primarily divided into Lignosulfonate, Kraft Lignin, and Other Product Types. Lignosulfonates continue to command a significant share of market revenue, driven by their established use across multiple industries. However, the report also tracks the growing revenue potential of specialized kraft lignin derivatives as purification costs decline. The differentiation between commodity-grade and specialty-grade lignin is a key theme, as margins vary significantly between bulk dispersants and high-performance functional fillers.
Lignin and Lignin-Based Products Market
By Application: Demand is driven by diverse end-use sectors including Dispersant, Concrete Additive, and Other Applications. The construction industry utilizes lignin-based additives to improve workability and reduce water content in concrete mixes. In the agricultural sector, lignin serves as a binder in animal feed pellets, which reduces pelleting energy use and improves feed conversion efficiency through better pellet durability. Additionally, lignin acts as a dispersant in fertilizer formulations to ensure uniform nutrient distribution. Our analysis breaks down the relative importance of these applications based on their contribution to total market revenue, helping clients identify the most profitable entry points.
By Region: Geographic revenue distribution is another critical component. The report evaluates performance across North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Regional analysis accounts for differences in pulp industry maturity, regulatory environments, and local demand for bio-based materials. For example, European markets often prioritize regulatory compliance and sustainability certifications, while Asian markets may focus on cost-effective industrial scale-up. Understanding these regional nuances allows for tailored market entry strategies.
Industry Dynamics: Regulations, Standards, and Innovation
The lignin market does not operate in a vacuum. A significant portion of our report is dedicated to the external dynamics that shape market behavior, including regulatory frameworks and technological breakthroughs.
Regulatory Environment: Compliance is a gatekeeper in key application segments. In the United States, lignin sulfonate is included on the National List as a synthetic substance allowed for use in organic production under the USDA AMS National Organic Program Document. This designation allows its use as a plant or soil amendment for dust suppression and as a chelating agent in crop production, opening access to the premium organic agriculture sector. In Europe, regulatory approvals have been a focal point. The re-authorization of lignin for use in animal feed within the EU, highlighted by developments involving Borregaard, removes a potential barrier to entry. Furthermore, Sappi Europe gained feed safety certification for lignin-based animal feed applications in October 2024, setting a benchmark for quality and safety that competitors must meet to compete in this high-value segment.
Technological Innovation: The pipeline for new lignin applications is expanding. A notable development is the operation of the LigniOx oxidation process demo plant, which started in January 2026 at the Metsä Fibre Äänekoski pulp mill. Capable of producing up to 2 tons of oxidized lignin per day, this pilot plant represents a step toward commercializing tailored lignin chemistry. Such innovations could unlock new performance characteristics, such as improved solubility or reactivity, which are essential for penetrating more demanding industrial applications like advanced materials or biofuels.
These dynamics create a shifting landscape where regulatory milestones and process innovations can accelerate adoption timelines or alter competitive positioning overnight. Our report synthesizes these events to provide a forward-looking view of market readiness and risk factors.
Strategic Value for 2026 Decision-Making
Why is this report essential for your strategic planning in 2026? The lignin market is at an inflection point where the gap between potential and realization is narrowing, but the path is still complex. Decision-makers need more than top-line numbers; they need actionable intelligence that connects market size to competitive reality.
First, the report provides a robust baseline for investment appraisal. By quantifying the revenue contribution of different sources, products, and applications, companies can prioritize projects that align with high-growth segments. Whether you are considering vertical integration into pulping processes or developing downstream formulation technologies, the segmentation data allows for scenario modeling based on realistic demand forecasts.
Second, the competitive profiling offers context for partnership and M&A strategies. Knowing who holds the market share, who is investing in R&D, and who has secured critical regulatory approvals allows you to identify potential allies or threats. For instance, understanding the specific capabilities of players like Green Agrochem in the fertilizer binder space or UPM in functional fillers can inform supply chain diversification or product differentiation strategies.
Third, the analysis of industry dynamics helps in risk management. Regulatory changes can quickly alter the viability of certain applications. By tracking certifications like feed safety standards and organic compliance, you can anticipate shifts in demand and adjust your product portfolio accordingly. Additionally, monitoring pilot plant operations and technological demonstrations provides early signals of future cost structures and performance capabilities that could disrupt current market equilibriums.
Conclusion
The Lignin Products Market offers a compelling value proposition for companies seeking to align with sustainability goals while capturing new revenue streams. However, success requires navigating a landscape defined by diverse feedstock sources, varied product specifications, and a competitive mix of integrated giants and specialized innovators. PW Consulting's market research report provides the depth and clarity needed to make informed decisions in this evolving environment.
While this overview highlights the strategic framework and key market drivers, it only scratches the surface of the comprehensive intelligence available. The full report contains detailed segmentation breakdowns, competitor analysis matrices, and granular data on regional revenue distributions that are essential for tactical execution. We invite you to access the complete study to gain the full picture of market opportunities and competitive dynamics. Discover how your organization can leverage the growing demand for lignin products to drive sustainable growth and secure a competitive advantage in the bio-based economy.
For detailed analysis of this topic, please visit the official page: Lignin Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Holographic Anti-Counterfeiting Market to Reach $985M by 2032, Growing at 4.0% CAGR
By PW Consulting, 2026-09-16
Illuminating the Path to Authenticity: Strategic Insights into the Holographic Anti-Counterfeiting Marks Market 2026–2032
In an era where counterfeit goods erode brand equity, compromise consumer safety, and violate global trade compliance, holographic anti-counterfeiting marks have evolved from decorative finishes into mission-critical security infrastructure. As regulatory scrutiny intensifies and supply chain vulnerabilities expose high-value products to sophisticated forgery, the demand for optically secure, tamper-evident, and instantly verifiable markings has never been more indispensable. At PW Consulting, we have authored a comprehensive market study that cuts through surface-level industry narratives to deliver an actionable, forward-looking intelligence framework. This article serves as a strategic preview of our latest research, outlining how the holographic anti-counterfeiting marks sector is positioned for measurable expansion, how structural market forces are reshaping competitive boundaries, and why procurement leaders, brand protection officers, and investors require granular, data-backed intelligence to navigate the 2026–2032 horizon.
Market Trajectory and the Strategic Imperative for 2026 Planning
Over the historical review window of 2020 through 2025, the global market for holographic anti-counterfeiting marks demonstrated consistent upward momentum, reflecting a structural shift from reactive anti-fraud measures to proactive, integrated authentication strategies. From a baseline of USD 620.0 million in 2020, market revenue progressed steadily to USD 754.0 million by 2025, signaling that optical security has transitioned from a niche compliance requirement to a mainstream operational priority across multiple product categories. This growth trajectory was not accidental; it reflects sustained industry investment in higher-fidelity optical features, broader deployment of tamper-evident overlays, and increasing reliance on holographic verification as a first-line defense against product duplication.
Looking ahead through the 2026–2032 forecast horizon, the expansion narrative continues with disciplined, compounding growth. The market is projected to advance from approximately USD 770.5 million in 2026 to USD 985.0 million by 2032, underpinned by a forecast period CAGR of 4.0 percent. This trajectory underscores a critical strategic reality for decision-makers: growth will not be driven by volume saturation alone, but by deepening penetration in regulated categories, rising demand for multi-layered authentication architectures, and geographic expansion in regions where enforcement frameworks are maturing. For enterprises mapping procurement budgets, supply chain security investments, and brand protection roadmaps in 2026, understanding how this growth distributes across technology formats, end-use categories, and regional enforcement climates is essential to avoiding misaligned capital allocation.
Our study is engineered specifically to address that planning gap. Instead of presenting a static snapshot, it contextualizes revenue progression within the operational factors that truly shape procurement and investment decisions: the pace of regulatory adoption, the evolution of optical master origination capabilities, the shift toward integrated security supply chains, and the competitive responses of established manufacturers and emerging innovators. By linking historical performance to forward-looking market engineering, the report provides a reliable compass for stakeholders who must translate market size into sourcing strategy, risk mitigation, and growth positioning.
The 2026 Landscape: Regulation, Standards, and Structural Demand Drivers
The current market environment is being redefined by a convergence of policy mandates, standardization initiatives, and technological maturity. One of the most consequential forces shaping demand is the tightening of regulatory frameworks that require visible, easily verifiable security features on high-risk consumer and industrial products. In regulated sectors, the presence of holographic seals is increasingly less about brand aesthetics and more about compliance feasibility, inspection efficiency, and liability management. As authorities enforce tamper-proof visual indicators and authentication protocols, organizations that delay integration of robust optical security face not only legal exposure but also the operational burden of retroactive packaging redesigns and supply chain disruptions.
Parallel to regulatory pressure, standardization efforts are elevating the technical expectations for optical security solutions. Industry bodies are reinforcing guidelines that help organizations verify authenticity, assess performance, and reduce ambiguity in supplier selection. The growing emphasis on documented verification methodologies and structured authentication standards means that procurement teams can no longer evaluate holographic marks solely on visual appearance or unit cost. They must assess durability, replication resistance, integration compatibility, and conformity with recognized authentication frameworks. This shift favors suppliers that can demonstrate technical rigor, repeatable production quality, and alignment with internationally acknowledged verification principles.
On the production side, the technical foundation of high-security holographic marks remains anchored in master origination. The creation of precise optical masters represents the most crucial step in manufacturing secure anti-counterfeiting features, because the fidelity of the final output is directly tied to the quality of the original recording process. Advanced laser-based photoresist recording and specialized origination systems are now essential for producing marks that withstand scrutiny from both end users and counterfeiters attempting replication. As a result, the market is gradually rewarding manufacturers that control or closely integrate master origination capabilities, rather than relying exclusively on commodity-style reprographic workflows.
These dynamics create a dual strategic implication for 2026. First, demand is becoming more specification-driven, with procurement decisions increasingly anchored in performance criteria, regulatory fit, and verification reliability. Second, competitive advantage is shifting toward firms that can offer end-to-end optical security engineering, from master creation to final label or film deployment, while maintaining traceability and consistency across production runs. Understanding how these forces interact across market segments is central to the analytical framework presented in our full study.
Market Architecture: Formats, Applications, and Regional Dynamics Without the Noise
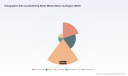
A central challenge for market participants is navigating structural segmentation without losing sight of total-market opportunities. Holographic anti-counterfeiting marks are delivered through multiple physical formats, each with distinct production considerations, integration requirements, and end-use suitability. Broadly, the market is anchored by holographic film-based solutions and holographic paper-based solutions, with film continuing to command the larger revenue share due to its broader adaptability in high-durability packaging, secure labeling, and multi-layer authentication architectures. Paper-based formats remain strategically relevant in applications where cost efficiency, print compatibility, and rapid deployment are prioritized. However, the operational choice between formats rarely hinges on substrate preference alone; it is increasingly defined by the required level of optical complexity, the environment in which the mark must survive, and the verification methods used by downstream inspectors and consumers.
On the application side, demand is dispersed across diverse end-use sectors, with particularly notable reliance in categories where product authenticity carries direct economic and safety implications. Tobacco products continue to represent a substantial share of deployment, driven by regulatory mandates for authentication marks and prominent health-warning compliance. Food and drink applications follow as another major demand channel, where brand trust, supply chain integrity, and consumer safety converge. The cosmetic sector also contributes meaningful volume, reflecting the premium-brand imperative to prevent counterfeiting and protect consumer confidence in high-margin personal care products. Beyond these core verticals, a broad residual category of applications spans documents, pharmaceuticals-adjacent packaging, luxury goods, and industrial components, reinforcing that holographic anti-counterfeiting marks are not confined to a single industry narrative but are becoming a cross-sector authentication layer.
Holographic Anti-counterfeiting Marks Market
Regionally, market distribution reflects the interplay of manufacturing capacity, enforcement maturity, and end-market density. Asia Pacific stands out as a significant revenue region, consistent with its scale in packaging production, industrial manufacturing, and fast-moving consumer goods ecosystems. North America and Europe remain influential demand centers, shaped by stringent regulatory expectations, strong brand-protection cultures, and well-established authentication practices. Latin America and the Middle East and Africa collectively represent meaningful but comparatively smaller revenue pools, with growth potential tied to improving compliance enforcement, expanding export-oriented production, and increasing adoption of standardized security marking practices.
Rather than fragmenting the analysis into isolated percentage breakdowns, our study interprets these structural patterns as interacting forces. It examines where format preferences align with application requirements, where regional enforcement frameworks accelerate adoption, and where supply-side capabilities are redefining market access. This integrated perspective allows readers to see not just where revenue is generated, but why it is generated there and how that positioning is likely to shift through 2032.
Competitive Dynamics: Consolidation, Capability, and the New Innovation Perimeter
The competitive landscape for holographic anti-counterfeiting marks is characterized by a blend of established multinational suppliers, specialized regional manufacturers, and technology-focused entrants expanding the innovation perimeter. Market concentration data indicates a moderately consolidated structure, with the top three players collectively accounting for approximately 45.0 percent of market revenue and the top five reaching around 55.0 percent. This concentration suggests that while scale and integrated capabilities provide meaningful advantages, there remains sufficient space for differentiated specialists to compete on technical novelty, regional responsiveness, and application-specific engineering.
Leading participants illustrate the breadth of strategic postures now shaping the sector. Suzhou Image Technology Co., Ltd. has built a long-standing presence in optical security production, offering custom holographic security labels, hologram stickers, laminate overlays, and anti-counterfeiting solutions with more than two decades of experience in the field. Its recent 20th anniversary celebration in April 2026 reinforced continuity in its security hologram focus, even as the broader market demands more sophisticated integration and verification support. In India, Holographic Security Marking Systems P. Ltd. has positioned itself as a pioneer in holographic security tapes, tamper-evident labels, hologram stickers, and void security seals, reflecting the rising regional importance of practical, enforcement-friendly authentication tools.
Everest Holovisions Limited contributes to the competitive mix through metalized holographic films and security holographic labels designed for enhanced product security, while AFC Hologram specializes in security holograms, holographic registered packaging, lens films, and 3D micro-nano relief structures that push the boundaries of replication difficulty. Shenzhen Holoart High Technology Company Limited and Light Logics Holography and Optics Pvt Ltd further expand the supply base with advanced holographic security features and optical security labels targeting packaging and consumer product authentication. In the flexible packaging and hybrid security domain, Uflex Limited has developed integrated solutions including holographic seals for brand authentication, demonstrating how packaging manufacturers can embed optical security directly into broader product protection strategies.
In Europe, Kurz has long been recognized for holographic security foils, labels, and anti-counterfeiting packaging solutions developed in collaboration with technology partners, highlighting the importance of cross-industry cooperation in maintaining high optical standards. In the United States, Crane Authentication Solutions provides advanced holographic and optical security markings for currency, documents, and products, while in the United Kingdom, De La Rue has advanced optical security through platforms such as OPTILIGHT™, extending holographic applications into high-security environments. HUECK FOLIEN GmbH adds further depth in Europe as a manufacturer of holographic security foils and labels for brand protection and anti-counterfeiting packaging. Kumbhat Holographics rounds out the competitive field as a specialist in holographic security markings and anti-counterfeiting solutions, reinforcing the continued presence of focused, application-oriented suppliers across multiple markets.
Recent industry developments underscore that competition is increasingly defined by collaboration, standardization, and ecosystem expansion as much as by product specifications. In May 2026, IOTA expanded its global anti-counterfeiting dialogue to include banknotes, brand protection, and secure documents, strengthening collaboration with member companies. Earlier in the year, IOTA launched a new membership category for optical security start-ups to foster innovation in anti-counterfeiting technologies, alongside the introduction of the DocCheck Analysts Insights tool to support document verification and authentication for members. These moves matter because they indicate a market in which technology validation, shared verification practices, and access to emerging innovators are becoming integral to competitive resilience.
For enterprise decision-makers, this dynamic environment carries a clear message: sourcing strategy cannot assume static supplier capabilities. Instead, organizations must assess manufacturers not only on current output but on their ability to evolve with regulatory expectations, integrate master origination and replication expertise, participate in authentication ecosystems, and adapt to new verification tools. The full report provides a structured competitive assessment that connects company profiles, strategic focus areas, and recent developments to the practical questions procurement and brand-protection teams face when selecting long-term security partners.
What the Study Delivers: From Macro Signals to Operational Decisions
PW Consulting’s Holographic Anti-Counterfeiting Marks Market study is built to bridge the gap between high-level market awareness and operational decision-making. The report combines long-term market sizing, segmentation interpretation, competitive profiling, and regulatory analysis into a single intelligence framework designed for action. Rather than presenting numbers in isolation, it situates them within the business context that determines their relevance: procurement planning, compliance readiness, technology selection, supplier evaluation, and long-range investment prioritization.
readers can expect detailed coverage of market evolution across the historical and forecast periods, with analysis of how revenue trends reflect shifting demand drivers, format preferences, and application adoption patterns. The study examines the structural logic behind segmentation, helping users understand where holographic film and holographic paper solutions are gaining traction, how application-specific requirements shape deployment strategies, and where regional enforcement and manufacturing dynamics influence market access. It also contextualizes competitive behavior by linking company capabilities and recent milestones to broader market forces, enabling more informed benchmarking and risk assessment.
Equally important is the report’s emphasis on practical interpretation. It addresses the operational significance of optical master origination, the role of specialized production equipment in maintaining high-security standards, and the implications of regulatory frameworks that mandate tamper-proof visual indicators and authentication features. By integrating these elements, the study helps organizations move beyond generic market descriptions and toward precise procurement and strategy decisions. For executives preparing 2026 budgets and three-to-five-year security roadmaps, that interpretive depth is essential. Core quantitative breakdowns, scenario-based sensitivity insights, and vendor-specific benchmarking detail are reserved for the full report, where they can be examined with the precision required for confident decision-making.
Why This Intelligence Matters for 2026 Strategic Planning
The 2026–2032 period will not simply be defined by continued market growth; it will be defined by how effectively organizations translate that growth into defensive advantage and commercial resilience. Holographic anti-counterfeiting marks are increasingly embedded in regulatory compliance, brand protection, and supply chain integrity strategies, which means the cost of incomplete market intelligence is rising. Companies that rely on fragmented data or surface-level market descriptions risk under-investing in the wrong formats, selecting suppliers misaligned with future authentication expectations, or misreading regional demand shifts that affect sourcing and product rollout timing.
This study is designed to reduce those risks. It helps procurement leaders evaluate format and application fit with greater confidence, enables brand-protection teams to align security investments with enforcement trends and verification standards, and supports executives in understanding where competitive concentration creates stability and where emerging innovators may reshape the value chain. With a forecast CAGR of 4.0 percent and revenue projected to approach USD 985.0 million by 2032, the market is large enough to matter and dynamic enough to reward those who plan with precision. The question is no longer whether optical security will continue to grow, but how organizations will position themselves to capture the right opportunities within that growth.
Access the Full Intelligence Framework
This preview has outlined the strategic logic behind the market’s trajectory, the forces reshaping competition, and the operational considerations that should guide 2026 decision-making. It has intentionally avoided presenting the full set of segmented revenue breakdowns, region-by-region percentage distributions, and application-level market shares that form the analytical backbone of the complete study. Those details are essential for precise planning, and they are available in the full report, where each figure is supported by methodological context, competitive interpretation, and implementation relevance.
Holographic Anti-Counterfeiting Trademark Market
For organizations that need to move from market awareness to actionable strategy, the complete PW Consulting Holographic Anti-Counterfeiting Marks Market study offers the depth, structure, and forward-looking perspective required to make informed choices in a rapidly evolving security landscape. To access the full dataset, segmentation analysis, competitive profiling, and forecast decomposition, please visit the source page for the complete market research.
For detailed analysis of this topic, please visit the official page: Holographic Anti-counterfeiting Marks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blood Bank Information Systems Market to Reach $1,580.8M by 2032, Growing at 7.8% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Next Wave: Inside the Blood Bank Information Systems Market Outlook 2026
The global blood bank information systems market is entering a phase of structural acceleration, driven by tightening regulatory frameworks, the digital transformation of transfusion workflows, and the financial imperative to convert legacy inventory operations into scalable, interoperable platforms. Our newly published market research report, Blood Bank Information Systems Market: Strategic Intelligence for the Next Wave 2026–2032 , maps this transition with executive-grade precision. Covering the historical baseline from 2020 through 2025 and projecting forward to 2032, the study translates complex operational, technological, and compliance forces into a decision-ready architecture for health systems, blood centers, procurement leaders, and investment teams.
For organizations planning cycles in 2026, the difference between reactive procurement and strategic positioning lies in understanding how macro trajectories intersect with grounded, operational realities. This report is engineered to deliver that clarity. Below is a preview of the analytical rigor, structural breakdowns, and competitive intelligence contained within our full dataset.
A Market Reaching an Inflection Point
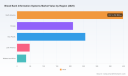
The industry has demonstrated sustained, compound growth over the past half-decade. From a historical revenue base of approximately 658.5 million USD in 2020, the market advanced through successive years of expansion, reaching 947.0 million USD in 2025. That progression is not merely a function of incremental digitization; it reflects a fundamental re-architecture of how blood is tracked, allocated, tested, and transfused across institutional and regional networks.
Looking ahead, the forecast trajectory indicates continued momentum, with the overall market projected to surpass the 1.5 billion USD threshold by 2032. The implied compound annual growth rate across the 2026–2032 forecast horizon stands at 7.8 percent. While these headline figures provide essential directional context, the strategic value for executives lies in what sits beneath them: the relative weight of deployment models, the pace of institutional adoption, the shifting cost structures associated with cloud architectures, and the compliance-driven procurement triggers that accelerate upgrade cycles.
Regulatory Acceleration as a Procurement Catalyst
Compliance has evolved from a baseline requirement into a dominant force shaping technology investment. In the United States, FDA regulations mandate that blood bank information systems support complete traceability from donor to recipient, eliminating gaps that previously allowed fragmented record-keeping to persist across standalone modules. Across the Atlantic, the European Union’s Substances of Human Origin (SoHO) Regulation introduces expectations for real-time, audit-ready data trails, placing a premium on systems capable of maintaining unbroken lineage documentation under live operational conditions.
These regulatory expectations are not theoretical. Recent industry data indicates that 72 percent of blood centers identify regulatory compliance as the primary driver for upgrading blood bank information systems. That dynamic reframes the purchasing conversation: organizations are no longer evaluating platforms primarily on incremental feature sets, but on their capacity to future-proof audit workflows, integrate with laboratory and electronic health record ecosystems, and withstand jurisdictional scrutiny without operational friction.
Architecture Shifts: From Capital-Seated Infrastructure to Scalable Deployment
A parallel transformation is underway in how these systems are provisioned. Traditional on-premises deployments, once the default model for institutional blood management platforms, are being re-evaluated against cloud-based architectures that reduce upfront capital expenditure while enabling elastic inventory management. Cloud delivery models allow blood centers and hospital networks to scale allocation logic, donor tracking, and inventory visibility without the rigidity of fixed infrastructure.
The strategic implication is nuanced. Lower capital barriers do not automatically translate into faster adoption; they introduce new considerations around data sovereignty, interoperability with legacy EHR environments, and the total cost of ownership across multi-year contracts. Our report examines these trade-offs explicitly, helping decision-makers align deployment strategies with institutional readiness, staffing capacity, and compliance calendars.
Functional Core: What the Systems Actually Do
At the operational level, blood bank information systems are converging around a shared set of functional imperatives, even as vendors differentiate through workflow design, integration depth, and compliance instrumentation. The core capabilities span several interconnected domains:
- Donation management workflows that coordinate scheduling, donor eligibility, collection tracking, and post-donation documentation across distributed intake sites.
- Transfusion service orchestration that links pre-transfusion testing, crossmatch logic, issue controls, and bedside allocation into a closed-loop process designed to reduce error surfaces.
- Inventory control and traceability that reconcile stock levels, expiration management, component segmentation, and quarantine protocols while maintaining donor-to-recipient lineage.
- Regulatory and standards alignment that hardcodes compliance checks, audit-ready reporting, and documentation practices aligned with accreditation bodies and jurisdictional requirements.
- Interoperability and integration that connect blood bank operations with laboratory information systems, hospital EHRs, and regional sharing networks.
Vendors approach these functions from different strategic angles. Some emphasize modular suites that can be deployed incrementally across inventory and point-of-care allocation workflows. Others position transfusion-centric platforms with embedded safety checks and compliance instrumentation built into daily operations. A further cohort structures their offerings around web-accessible blood bank and transfusion service environments designed to standardize pre-transfusion testing, inventory control, and accreditation alignment. Still others embed blood bank functionality inside broader electronic health record platforms, pursuing integrated donor, inventory, and transfusion workflows within a unified clinical ecosystem.
Evaluating these approaches requires more than feature comparison. It requires understanding which architecture maps to an institution’s existing integration maturity, which compliance obligations are most immediate, and which operational pain points are severe enough to justify migration or expansion. The report provides the structured lens required to make that assessment without defaulting to vendor-led narratives.
Competitive Landscape: Concentration, Differentiation, and Recent Moves
Market concentration in this sector remains relatively distributed. Aggregate data indicates that the top three competitors account for roughly 26.8 percent of total market revenue, while the top five capture approximately 34.5 percent. That structure suggests room for specialized differentiation, regional expansion, and workflow-specific positioning, even as larger platforms leverage scale and integration breadth.
Blood Bank Information Systems Market
Several established players define the current competitive frontier. Haemonetics offers a modular blood bank information system portfolio designed to support inventory control, traceability, point-of-care allocation, and safe transfusion workflows. WellSky has built a transfusion blood bank information system with embedded safety checks, EHR and laboratory integration, and compliance tools oriented toward patient safety and operational continuity. SCC Soft Computer provides a web-based blood bank and transfusion service information management environment that incorporates pre-transfusion testing, inventory control, and alignment with AABB and FDA expectations. Mediware Information Systems delivers blood bank information system modules focused on transfusion service management, inventory control, and regulatory compliance. Cerner Corporation approaches the category from within its broader electronic health record platform, pursuing integrated donor, inventory, and transfusion workflows as part of a connected clinical architecture.
Recent activity among these leaders underscores how the market is evolving in practice. In early 2026, WellSky advanced its transfusion platform with a new kits feature focused on inventory and workflow optimization for blood banks, reflecting a continued emphasis on operational efficiency within compliance-oriented environments. Later in the year, SCC Soft Computer participated in a major regional conference in Australia, showcasing its web-based blood bank system and signaling ongoing attention to international deployment contexts and demonstration-led engagement. These moves are representative of broader patterns: the push toward workflow refinement, the emphasis on modular or web-accessible architectures, and the continued relevance of live demonstration and conference-based engagement in a sector where trust, compliance, and operational fit dominate procurement decisions.
Report Scope: What Decision-Makers Will Find Inside
Our full study is built for executives who need more than directional trends. It is structured to support procurement strategy, portfolio planning, competitive positioning, and investment prioritization across the 2026–2032 horizon. The report includes:
- Historical and forecast market sizing from the 2020 baseline through the 2032 projection, with attention to the pace of growth across the forecast window and the inflection points that shape planning assumptions.
- Functional and adoption-oriented segmentation that breaks down how demand distributes across core system types and major application environments, enabling readers to understand where operational concentration lies and which contexts are expanding most rapidly.
- Regional demand architecture that contextualizes how mature and emerging markets differ in infrastructure readiness, compliance pressure, and procurement cadence, without reducing the analysis to static share rankings.
- Deployment and cost-structure analysis covering the shift toward cloud-based delivery, its implications for capital expenditure, scalability, inventory management, and integration effort.
- Competitive profiling of the leading platforms, including functional positioning, integration strategies, compliance emphasis, and recent product and market activities that signal likely direction.
- Regulatory and reimbursement context that maps FDA traceability expectations, EU SoHO audit-trail requirements, and the compliance-driven upgrade behavior observed across blood centers.
- Strategic implications for 2026 planning that translate the data into procurement timing, vendor evaluation criteria, integration prioritization, and risk management considerations.
Throughout the report, the emphasis remains on usable intelligence rather than abstract sizing. The objective is to help leadership teams determine not only where the market is moving, but how that movement should change operational planning, vendor selection, and compliance readiness in the near term.
Blood Bank Market
Why This Research Matters for 2026 Decisions
The 2026 planning cycle coincides with a convergence of pressures that make blood bank information systems a strategic subject rather than a purely operational one. Regulatory obligations are tightening across major jurisdictions. Cloud delivery is reshaping cost expectations and deployment flexibility. Integration with laboratory and EHR environments is becoming a threshold requirement rather than a differentiator. And compliance-driven upgrade behavior is accelerating procurement conversations that previously unfolded over multi-year horizons.
In that environment, incomplete market intelligence carries real cost. Decision-makers who rely on high-level trends without segment-level clarity may misjudge where adoption is actually concentrated. Teams that evaluate vendors without a structured view of compliance fit, integration debt, and deployment economics may overinvest in features that do not reduce operational risk. Organizations that treat regulatory alignment as an afterthought may find themselves forced into reactive migrations under audit pressure.
Our report is designed to reduce those uncertainties. By combining macro trajectory, functional segmentation, competitive positioning, and compliance context into a single analytical framework, it enables leaders to evaluate architectural choices, procurement timing, and vendor fit with greater confidence. The headline growth trajectory and the 7.8 percent forecast compound rate provide the strategic backdrop; the actionable intelligence lies in the structural breakdowns, adoption patterns, and competitive dynamics that explain how that growth is being generated and where it is likely to concentrate.
Preview, Not Replacement
This article provides a directional lens into the full study, but it cannot substitute for the data depth, comparative tables, and segment-level analysis contained in the complete report. The specific breakdowns that allow procurement teams to map demand concentration, evaluate regional readiness, and benchmark competitive positioning are developed in detail within our published dataset. Those insights are central to building defensible 2026 strategies, and they are best reviewed in the full analytical context.
For executives, analysts, and procurement leaders responsible for blood bank information systems planning, the report offers a structured foundation for evaluating where to invest, what to prioritize, and how to align technology decisions with compliance, interoperability, and operational resilience goals. The market’s next phase will reward organizations that can translate regulatory pressure, deployment flexibility, and integration requirements into disciplined, evidence-based choices. Our research is intended to support exactly that process.
For detailed analysis of this topic, please visit the official page: Blood Bank Information Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bike Shifting Services in Noida: A Reliable Guide for Easy Two-Wheeler Relocation
By carbikemovers, 2026-09-16
Relocating a motorcycle or scooter can become an important part of moving to a new city. Whether you are changing jobs, shifting your family, moving for education, or sending a vehicle to someone, transporting a two-wheeler requires careful coordination. Riding the bike over a long distance may not always be convenient, particularly when other relocation tasks are already taking up your time.
Professional bike shifting services in noida offer an organized way to move motorcycles and scooters from Noida to different destinations. A transportation provider can coordinate the major stages of the process, including pickup, vehicle inspection, protective preparation, loading, transportation, unloading, and delivery.
For Noida residents, understanding the available process and preparing the bike correctly can make transportation easier to manage. From selecting a suitable service to checking the vehicle at delivery, every stage can contribute to a smoother relocation experience.
Why Bike Shifting Is Useful During Relocation
Moving to another city often involves several simultaneous responsibilities. You may need to arrange household goods, travel, accommodation, documentation, and work-related requirements.
Adding a long-distance bike ride to this list may create additional pressure. A professional shifting service allows the owner to arrange transportation for the bike separately.
This can be especially useful for people travelling by train or flight. Instead of planning a road journey around the relocation, the customer can coordinate the bike's pickup and delivery according to the transportation schedule.
Professional bike shifting in noida can also be useful for customers who are purchasing a two-wheeler from another location or sending their vehicle to family members.
Types of Customers Who May Need Bike Shifting
Different situations can create a need for two-wheeler transportation.
Job Relocation
Employees frequently move between cities because of transfers or new employment opportunities. Transporting their existing bike can help them maintain their preferred mode of local transportation after relocation.
Education-Related Moves
Students moving from Noida to another city may want to take their scooter or motorcycle with them. Professional shifting can provide an alternative to riding a long distance.
Family Relocation
When an entire family changes residence, there may already be several household moving arrangements to manage. Separate bike transportation can simplify the vehicle portion of the move.
Vehicle Purchase
A motorcycle purchased outside Noida may need to be transported to the buyer's location. Professional transportation can help coordinate the delivery.
Sending a Bike to Relatives
Owners may also need to move a two-wheeler to parents, siblings, or other family members living in another city.
How to Plan Your Bike Shift
Good planning begins with collecting the right information.
Start by identifying the exact pickup and delivery addresses. Make sure the contact details for both locations are accurate.
Next, note the bike's model and relevant vehicle information. Share these details with the transporter so the appropriate transportation arrangement can be discussed.
Choose a preferred pickup date and ask about the expected delivery timeline. If you are moving on a fixed schedule, mention this before booking.
Finally, request a clear quotation and understand what is included in the service.
The Bike Shifting Process Explained
The exact procedure can vary between transportation providers, but a typical bike shifting process involves several stages.
Booking
The customer provides information about the bike, route, pickup location, destination, and preferred schedule.
Pickup
The transporter coordinates collection of the motorcycle or scooter from the agreed location.
Inspection
The bike can be inspected before loading. Customers should record its condition using photographs.
Protective Preparation
Suitable protective materials may be used to reduce the possibility of scratches or marks during handling and transit.
Loading
The bike is carefully positioned and secured for transportation.
Transit
The vehicle travels toward the destination according to the planned logistics arrangement. Delivery time can vary depending on distance, route, traffic, weather, and operational factors.
Unloading and Delivery
At the destination, the bike is unloaded and handed over to the customer or authorized recipient.
Preparing Your Motorcycle or Scooter
Vehicle preparation should be completed before the scheduled pickup.
Wash the bike and check its overall visible condition. Pay attention to existing scratches, dents, paint marks, mirrors, lights, and other exterior components.
Take photographs from multiple angles. These images can serve as a condition record.
Remove all unnecessary personal items. Helmets, bags, documents, chargers, and other loose belongings should generally be taken out of the bike.
Keep the required vehicle documents ready according to the transporter's instructions.
Also follow any instructions regarding fuel, battery, or other mechanical preparation.
If your vehicle has a known mechanical issue, tell the transporter before pickup. Accurate information can help the provider plan the handling process appropriately.
Understanding Bike Shifting Charges
The cost of bike shifting in noida depends on the requirements of each shipment. There is no single price applicable to every bike.
Several factors can influence the quotation.
Distance: A longer route usually requires greater transportation resources.
Bike type: Different motorcycles and scooters may require different handling arrangements.
Pickup location: Difficult-to-access areas may require additional coordination.
Destination: Delivery requirements vary according to location and accessibility.
Packing: Protective preparation may influence the total service cost.
Doorstep service: Pickup or delivery directly at an address may affect the quotation.
Special requirements: Specific scheduling or additional handling requirements can also influence the final price.
Customers should ask for a detailed quotation and confirm whether any additional charges may apply.
What to Check Before Selecting a Service
Choosing a bike shifting provider should involve more than checking the lowest quotation.
First, confirm that the provider covers your required route. Then ask how the bike will be packed, loaded, transported, and delivered.
Check whether the quoted price includes the major stages of transportation. If any service is charged separately, understand the additional cost before booking.
Ask about the expected delivery timeframe and how updates will be communicated.
You should also confirm the documentation requirements and payment terms.
Clear information at the beginning can help prevent misunderstandings during the shifting process.
Common Problems Caused by Poor Planning
Last-minute arrangements can create unnecessary complications. Customers may not have enough time to prepare documents or coordinate pickup.
Incorrect addresses can also cause delivery delays. Always double-check the pickup and destination information.
Another common issue is failing to document the bike's condition. Photographs should be taken before handing over the vehicle.
Customers should also avoid leaving valuables inside the bike. Personal belongings should be removed before transportation unless the service provider specifically permits otherwise.
Finally, do not assume that all transportation companies follow the same procedures. Discuss the important details before confirming your booking.
Why Choose Carbikemovers?
Carbikemovers provides vehicle transportation solutions for customers who need to move motorcycles and scooters between cities. Its service process can cover important stages such as pickup coordination, vehicle preparation, loading, transportation, unloading, and delivery.
Customers looking for bike shifting in noida can share their bike details, pickup location, destination, and scheduling requirements before arranging transportation.
For employees, students, families, vehicle buyers, and other customers, professional transportation can provide a convenient way to relocate a two-wheeler without adding a long-distance ride to their moving plans.
A Pre-Shifting Checklist
Before handing over your bike, keep the following checklist ready:
-
Confirm the pickup and destination addresses.
-
Check the transportation quotation.
-
Ask about packing arrangements.
-
Confirm the pickup date and time.
-
Prepare required documents.
-
Clean and inspect the bike.
-
Take photographs of its condition.
-
Remove personal belongings.
-
Follow fuel-related instructions.
-
Keep the transporter's contact information accessible.
Following these basic steps can make the shifting process more organized.
What to Do After Delivery
Once your bike reaches the destination, inspect it before completing the handover.
Check the body panels, mirrors, wheels, lights, fuel tank, and other visible areas. Compare the condition with the photographs taken before pickup.
If everything is in order, complete the delivery formalities according to the service terms.
If you notice any issue, report it promptly through the appropriate communication channel provided by the transporter.
Keeping your booking information and condition photographs until the process is fully completed is a useful practice.
Conclusion
A motorcycle or scooter can be an important part of a relocation, but moving it over a long distance does not always require the owner to ride it. Professional bike shifting services in noida provide an organized alternative for customers who need to transport their two-wheelers between cities.
Proper preparation is essential. Customers should document the vehicle's condition, arrange the necessary documents, understand the quotation, confirm the pickup schedule, and discuss delivery expectations before booking.
For anyone searching for dependable bike shifting in noida , selecting a professional transportation service and planning each stage in advance can make the overall two-wheeler relocation process more convenient and manageable.
FAQs
1. Can I shift my bike from Noida to another state?
Yes, two-wheeler transportation can be arranged between Noida and various destinations depending on the route and service availability.
2. How should I document my bike before shifting?
Clean the bike and take clear photographs from the front, rear, both sides, wheels, and other visible areas. Photograph any existing scratches or dents separately.
3. What factors affect bike shifting charges?
Distance, bike model, pickup and delivery locations, packing requirements, doorstep services, and additional transportation requirements can influence the quotation.
4. Can my scooter be transported through bike shifting services?
Yes, scooters can generally be transported through professional two-wheeler shifting services. The exact arrangement depends on the vehicle and route.
5. What should I check when my bike reaches the destination?
Inspect the bike for visible scratches, dents, or other changes and compare its condition with your pre-shifting photographs. Complete the delivery formalities after checking the vehicle.
PW Consulting: DDoS Protection Market Hits $2.15B in 2025, Projected 13.83% CAGR to $5.38B by 2032
By PW Consulting, 2026-09-16
Navigating the New Perimeter: Strategic Imperatives in the 2026 DDoS Protection and Mitigation Market
The cybersecurity landscape of 2026 is defined by a fundamental shift in how enterprises conceptualize their network boundaries. As digital transformation accelerates and hybrid work models become entrenched, the attack surface has expanded exponentially. Distributed Denial of Service (DDoS) attacks have evolved from mere nuisances into sophisticated weapons capable of crippling critical infrastructure, disrupting supply chains, and eroding consumer trust. In this high-stakes environment, investing in robust DDoS protection is no longer a discretionary IT expense but a core component of enterprise risk management. Our latest market research offers a comprehensive lens through which to view this rapidly evolving sector, providing the intelligence necessary for strategic decision-making in the coming years.
This report serves as a critical compass for stakeholders navigating the DDoS Protection and Mitigation Market. By analyzing historical trajectories and forecasting future growth, we uncover the underlying forces driving demand. The research is designed not merely to report numbers but to contextualize them within the broader operational and technological realities facing Chief Information Security Officers (CISOs), procurement leaders, and investors. Understanding the market dynamics allows organizations to align their security postures with business resilience goals, ensuring that protection mechanisms scale effectively alongside digital ambitions.
Market Trajectory and Growth Dynamics
The historical data from 2020 to 2025 indicates a steady and significant expansion in the sector, reflecting the increasing frequency and complexity of cyber threats. The market has demonstrated resilience and consistent upward momentum, driven by the universal need for uptime and availability. Our analysis projects this trajectory to continue robustly through the forecast period ending in 2032. The compound annual growth rate (CAGR) underscores the velocity of this expansion, signaling sustained investment across the industry value chain.
Such growth is not uniform across all vectors. It is propelled by the convergence of several macro factors. First, the proliferation of Internet of Things (IoT) devices provides attackers with larger botnets, necessitating more advanced mitigation capabilities. Second, the shift toward cloud-native architectures requires protection layers that are equally elastic and distributed. Third, regulatory pressures are forcing organizations in critical sectors to adopt stricter resilience standards. These dynamics collectively create a fertile ground for market expansion.
For enterprise decision-makers, this growth trajectory implies that the window for implementing foundational security measures is narrowing. Delaying investment in DDoS mitigation exposes organizations to escalating risks as attack volumes increase. The market data suggests that solutions must be scalable to handle future threat landscapes. Investing now positions organizations to leverage mature technologies rather than scrambling for ad-hoc solutions during a crisis. The financial magnitude of the market reflects the critical value businesses place on continuity.
Key Report Contents and Operational Insights
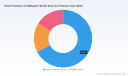
Our research goes beyond high-level figures to provide actionable intelligence. The report is structured to guide strategic planning across multiple dimensions. One primary focus is the breakdown of deployment models. Understanding the trade-offs between cloud-based, hybrid, and on-premises solutions is vital for architecture planning. Each model offers distinct advantages regarding latency, control, and scalability. The analysis details how organizations are balancing these factors to achieve optimal protection without sacrificing performance.
Similarly, the report examines protection types, dissecting the market by network-based, application-based, and host-based solutions. This segmentation is crucial because attacks target different layers of the stack. A comprehensive security strategy often requires a layered approach. By understanding the prevalence and effectiveness of each protection type, leaders can construct a defense-in-depth strategy that closes gaps. The research highlights where investments are flowing and which technologies are gaining traction based on efficacy and ease of integration.
Furthermore, the study addresses the operational realities of managing DDoS protection. This includes the growing emphasis on automation and real-time response. Manual mitigation is no longer sufficient given the speed of modern attacks. The report explores how vendors are integrating threat intelligence and automated rulesets to reduce response times. It also considers the human element, discussing the skills required to manage these systems and the potential impact on operational overhead. For procurement teams, this section offers criteria for evaluating vendor capabilities beyond marketing claims.
DDoS Protection and Mitigation Market
Competitive Landscape and Vendor Ecosystem
The market features a diverse mix of established giants and specialized security firms. Our analysis profiles key players who are shaping the competitive dynamics. Companies such as Akamai Technologies and Cloudflare have set high bars with their global anycast networks and dedicated protection platforms. Akamai focuses on robust behavioral defense across deployment options, while Cloudflare emphasizes integrated CDN scrubbing and bot defense. These firms represent the scale required to absorb massive volumetric attacks.
Other significant contributors include Imperva and Radware, which offer multi-layered protection services covering networks, applications, APIs, and DNS. Imperva leverages automated mitigation and threat intelligence to provide comprehensive coverage. Radware is notable for its hybrid approach, combining on-premise appliances with cloud scrubbing centers to deliver adaptive real-time mitigation. Their recent initiatives highlight the industry's move toward low-latency solutions and AI-driven security platforms, ensuring scalable application security enforcement without compromise.
Network infrastructure specialists like NETSCOUT and F5 Networks also play pivotal roles. NETSCOUT's Arbor portfolio targets enterprise-scale volumetric attacks with specialized perimeter defense tools. F5 integrates DDoS protection within its broader distributed cloud services, combining WAF and bot mitigation in a multi-cloud SaaS platform. Specialized vendors like Corero Network Security focus on high-performance distributed defense for service providers and enterprises, expanding their reach into new regions to address localized threats. The competitive landscape is characterized by continuous innovation, partnerships, and infrastructure expansion, such as the recent increase in global scrubbing capacity by telecommunications providers.
Industry Dynamics and Strategic Drivers
Several external factors are influencing the market dynamics beyond pure technology competition. Regulatory environments are becoming stricter. For instance, mandates in regions like the European Union require operators in critical sectors to meet specific resilience standards and reporting requirements within tight timeframes. This regulatory pressure compels organizations to adopt certified or compliant DDoS mitigation strategies, driving demand for solutions that can demonstrate adherence to these standards.
Infrastructure costs and energy considerations are also entering the conversation. Data center electricity demand is a growing concern, potentially affecting operational costs for hosting security infrastructure. Mitigation services that are energy-efficient or leverage optimized fiber optic transmission can offer long-term cost advantages. Additionally, the physical resilience of data centers is under scrutiny, as cybercrime-related attacks have historically caused unplanned outages. Ensuring that protection services are housed in resilient facilities is part of the broader due diligence process.
The rise of specialized use cases, such as gaming and real-time communications, is driving niche innovation. Recent product launches indicate a focus on low-latency mitigation for specific protocols, ensuring that security does not degrade user experience. Partnerships between security vendors and telecom providers are expanding reach and capacity, creating a more interconnected defense ecosystem. These developments suggest that the market is maturing from a commodity service into a specialized utility critical for digital operations.
Strategic Value for 2026 Decision-Makers
For leaders navigating 2026, this research provides the evidence base needed to justify security investments. The data supports the argument that DDoS protection is a foundational requirement for digital business. By understanding the market size and growth rates, CFOs and CEOs can contextualize security budgets within the broader risk profile of the organization. The segmentation analysis helps CTOs decide where to allocate resources, whether toward cloud migration, hybrid architectures, or specialized application layer defenses.
The competitive profiling allows procurement teams to benchmark vendor offerings. Knowing the specific strengths of players like Akamai, Cloudflare, Imperva, and others enables more informed RFPs and negotiations. It helps organizations avoid vendor lock-in by understanding the differentiated value propositions in the market. Furthermore, awareness of recent developments, such as regional expansions and infrastructure upgrades, informs decisions about service level agreements and geographic coverage.
Ultimately, this report is designed to transform uncertainty into strategy. The DDoS Protection and Mitigation Market is growing, but so are the threats. Making informed choices now ensures that security architecture supports business growth rather than hindering it. The insights contained within this study are intended to empower stakeholders to build resilience that lasts beyond the current threat cycle.
To access the full depth of this analysis, including detailed segmentation data, comprehensive vendor profiles, and granular forecast models, we invite you to explore the complete report. The full intelligence package provides the specific metrics and strategic recommendations required to execute your security roadmap with confidence. Discover the detailed data behind the trends and equip your organization with the knowledge to secure its digital future.
Worldwide Military Cyber Weapons Market
For detailed analysis of this topic, please visit the official page: DDoS Protection and Mitigation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LED Street Lighting Market to Hit $13.479B by 2032 with 5.28% CAGR
By PW Consulting, 2026-09-16
Navigating the Next Wave of Urban Infrastructure: Strategic Intelligence for the Global LED Street Lighting Market
As municipalities worldwide accelerate infrastructure modernization and sustainability mandates tighten, the global LED street lighting market stands at a critical inflection point. For executives, procurement leaders, and urban planners, understanding the trajectory of this market is no longer optional. It is a strategic imperative. PW Consulting is pleased to introduce our latest comprehensive market research, designed to equip decision-makers with the actionable intelligence required to navigate the forecast period from 2026 to 2032 and beyond.
Macro Trajectory and Revenue Context
The market has demonstrated consistent expansion over the past five years. Drawing from historical tracking between 2020 and 2025, revenue has climbed steadily from approximately 7.6 billion to nearly 9.4 billion USD. Looking forward, the forecast period positions annual revenue to surpass the 9.8 billion mark in 2026, with continued upward momentum projected through 2032. The compound annual growth rate for this forecast window is estimated at 5.28 percent, reflecting sustained demand drivers including municipal energy retrofit programs, aging infrastructure replacement cycles, and the integration of smart connected controls. These figures establish a clear baseline for capital allocation, partnership evaluation, and long-term portfolio planning. Rather than treating LED street lighting as a passive commodity replacement, organizations must recognize it as a dynamic market segment where technology refresh, regulatory alignment, and operational efficiency converge.
LED Lighting Market
Rising Input Costs and Material Market Realities
Cost volatility in raw materials introduces a layer of operational complexity that cannot be ignored in 2026 procurement strategies. Prices for essential metals and conductive materials have experienced notable pressure. Silver prices have risen sharply over the trailing twelve months, while copper has crossed significant thresholds in early 2026. These movements directly influence component manufacturing, fixture assembly costs, and supply chain pricing structures. For buyers and vendors alike, understanding how material cost fluctuations cascade through bill-of-materials, margin structures, and tender evaluations is essential. Forward-looking procurement requires scenario planning, multi-sourcing strategies, and a clear understanding of which cost drivers are transitory versus structurally embedded in the market.
Regulatory Momentum and Municipal Energy Mandates
Policy and regulatory frameworks continue to shape deployment velocity. In the United States, federal and state-level energy programs project that LED street lighting installations will dominate the majority of lighting installations by 2035, yielding annual energy savings exceeding 569 terawatt-hours. Such projections reinforce the financial case for early adoption and provide long-term visibility for manufacturers and system integrators. Meanwhile, structural shifts in other regions have created parallel opportunities. In Brazil, the transfer of public street lighting assets to municipalities created strong incentives for energy-efficient LED retrofits, particularly in markets facing elevated electricity costs. With a substantial share of municipalities now directly responsible for energy expenditures, the economic mechanics of lighting upgrades have shifted from centralized utility planning to localized budgetary decision-making. These regulatory transitions alter who controls procurement, how payback periods are evaluated, and which financing models gain traction.
What This Research Delivers: Operational Depth for Decision-Makers
Our market research is structured to move beyond headline figures and deliver operationally relevant intelligence. The publication provides a granular mapping of market segmentation, competitive positioning, and demand drivers across multiple dimensions. Readers will gain clarity on how product architectures are evolving under the broader shift toward LED-dominant installations, including the performance characteristics that municipal buyers now prioritize. The report examines application-specific deployment patterns across roadways, highways, and other municipal and utility contexts, explaining how usage environments influence luminaire specifications, optical requirements, and lifecycle expectations. Regional demand dynamics are contextualized to highlight where infrastructure budgets, electrification goals, and retrofit programs are most concentrated, enabling targeted market entry and expansion strategies. Crucially, the analysis integrates supply-side realities with end-user purchasing behavior, ensuring that revenue forecasts are anchored in market mechanics rather than extrapolated trends.
Competitive Landscape and Strategic Positioning
The market exhibits meaningful concentration among established players, with top-tier firms accounting for a substantial share of total industry revenue. This competitive density rewards companies that can differentiate through performance credentials, control integration, service ecosystems, and regional execution capability. Several core enterprises define the current competitive frontier. Acuity Brands delivers roadway luminaires and integrated smart controls tailored to municipal street and roadway applications. Signify Holding provides connected smart street lighting systems and a broad portfolio of road and street LED luminaires designed for urban infrastructure. Eaton Corporation contributes high-efficacy LED cobrahead and roadway luminaires for municipal street lighting projects, emphasizing reliable illumination performance. Cree Lighting manufactures high-efficiency LED street and roadway fixtures aimed at municipal and transportation applications. LEOTEK specializes in energy-efficient LED street light fixtures and complete citywide upgrade solutions, while Evluma manufactures energy-efficient LED roadway luminaire series for utilities and municipalities. TRT Lighting produces configurable LED street and highway lantern ranges for roadway applications. ZGSM manufactures high-efficacy LED street lights with tool-free maintenance for municipal roads, and Schréder provides full-spectrum outdoor lighting solutions including LED street luminaires for urban infrastructure. Together, these players illustrate a market where hardware performance, smart control interoperability, and municipal service readiness are increasingly decisive.
Recent Product Launches and Innovation Signals
Product introductions in early 2026 underscore the pace of technical refinement and market responsiveness. Evluma launched a new roadway luminaire series featuring modular design, broad lumen packages, high surge protection, and low-glare optics, targeting both utility and municipal applications. ZGSM introduced an updated cobra head LED street light series with high luminous efficacy, asymmetric distribution options, tool-free maintenance, and recognized certification for roads and urban applications. These releases signal several strategic themes. Modularity supports serviceability and component-level upgrades. Thermal and optical refinements address comfort and compliance requirements. Certification and distribution flexibility reduce friction in municipal qualification processes. For competitors and buyers alike, these launches are not isolated events; they are indicators of where performance thresholds are rising and how manufacturers are working to reduce total cost of ownership across installation, operation, and maintenance phases.
Implications for 2026 Corporate Strategy
For organizations operating in or adjacent to this market, the strategic implications are direct and time-sensitive. First, procurement and sourcing strategies must account for material cost volatility, particularly for metals and conductive components that influence fixture economics. Teams should evaluate contract structures, inventory buffers, and supplier diversification to protect margin stability. Second, product and portfolio planning should align with the growing emphasis on efficiency, optical quality, surge resilience, and maintainability. Specifications that once served as differentiators are increasingly becoming baseline expectations in municipal tenders. Third, smart control integration and interoperability are becoming strategic assets. Municipalities and utilities are looking beyond illumination output to network compatibility, remote management, and data-enabled maintenance. Vendors that can credibly support these requirements gain access to broader system-level engagements. Fourth, regional strategy should be informed by asset ownership models and energy cost structures. In markets where municipalities directly control lighting budgets and energy expenditures, the value proposition shifts toward measurable savings, rapid deployment, and lifecycle service support. In regions with centralized utility planning, standardization and compliance credentials may carry greater weight. Finally, competitive positioning requires clarity on whether a company competes on performance leadership, cost efficiency, regional reach, or integrated solutions. The market concentration profile indicates that scale and portfolio breadth remain important, but differentiation in specific application segments and service models can still create defensible positions.
Conclusion: From Observation to Actionable Intelligence
The LED street lighting market is evolving under the combined influence of infrastructure renewal, energy efficiency mandates, material cost dynamics, and rapid product innovation. For leaders tasked with capital planning, product strategy, partnership decisions, and regional expansion, high-level trends are necessary but insufficient. The full 2026 to 2032 forecast, segmentation analysis, competitive profiling, and regulatory context are essential to convert market awareness into executable strategy. PW Consulting's complete market research consolidates these dimensions into a single decision-ready framework, enabling executives to stress-test assumptions, identify priority opportunities, and align investments with the direction of demand. To access the full dataset, detailed segmentation breakdowns, competitive benchmarking, and strategic scenario guidance, we invite you to explore the complete report through our primary research portal. The strategic clarity required for 2026 begins with the right intelligence.
LED Street Lighting Market
For detailed analysis of this topic, please visit the official page: LED Street Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ITSM Market Hits $215M in 2025, Projected 16.45% CAGR Through 2032
By PW Consulting, 2026-09-16
The ITSM Software Market in 2026: Navigating Autonomous Service Delivery and Strategic Alignment
The landscape of IT Service Management (ITSM) software is undergoing a profound transformation in 2026, driven by the convergence of artificial intelligence, evolving compliance mandates, and the relentless push toward operational efficiency. As enterprises grapple with increasing data subject requests and the need for faster resolution times, the choice of ITSM platform has become a critical strategic decision rather than a mere operational tactic. This market research report provides a comprehensive examination of the ITSM software market, offering decision-makers the intelligence required to navigate this complex ecosystem with confidence.
Understanding the trajectory of this market is essential for stakeholders involved in digital transformation, IT operations, and service delivery strategy. The shift from traditional ticketing systems to autonomous, AI-driven service management platforms is redefining value propositions and competitive dynamics. This article serves as an introduction to our latest deep-dive analysis, highlighting the macro trends, competitive forces, and operational dynamics that are shaping the future of ITSM through 2032.
Macro Market Trajectory and Growth Dynamics
The ITSM software market has demonstrated consistent expansion over the past half-decade, reflecting the critical dependency organizations have on robust service management frameworks. Historical data from 2020 through 2025 shows a steady climb in revenue, indicating that investment in service management tools is viewed as a foundational element of enterprise infrastructure. As we move into the forecast period spanning 2026 to 2032, the growth trajectory accelerates, underpinned by the widespread adoption of cloud-based solutions and the integration of generative AI capabilities into core ITSM workflows.
Projections for the coming years suggest that the total market size will reach new thresholds, with significant year-over-year growth expected throughout the forecast period. This expansion is not merely a function of inflation or headcount growth but represents a structural shift in how IT services are delivered and consumed. Organizations are increasingly willing to invest in platforms that offer autonomous capabilities, reducing the burden on human agents while improving service levels. The compound annual growth rate observed in this market underscores the urgency for businesses to evaluate their current tooling against future-state requirements.
Strategic decision-makers must recognize that the market is maturing rapidly. Early adopters of advanced ITSM solutions are already reporting tangible benefits in terms of ticket deflection and resolution speed, creating a competitive pressure for others to modernize. Ignoring these trends risks falling behind in operational efficiency and service quality. Our report provides the necessary context to understand where the market stands today and where it is headed, enabling leaders to time their investments appropriately.
Software Asset Management Managed Service Market
Core Market Dynamics and Operational Pressures
Several key dynamics are exerting pressure on the ITSM market, compelling organizations to seek more sophisticated solutions. Labor costs remain a primary concern, as AI-powered ITSM platforms enable substantial ticket deflection and faster resolution times, reducing the reliance on specialized human labor for routine tasks. This shift allows IT teams to focus on higher-value initiatives while automated systems handle the volume of standard requests.
Simultaneously, data privacy and compliance requirements are intensifying. Enterprises are experiencing a dramatic increase in data subject requests, which drives demand for ITSM platforms equipped with built-in compliance features and audit-ready capabilities. The ability to manage these requests within a governed workflow is becoming a differentiator for vendors and a necessity for buyers.
Infrastructure trends further influence the market, with cloud-based ITSM solutions enabling scalable multi-cloud and hybrid deployments. Real-time service visibility and adherence to service level agreements are critical in these distributed environments. Furthermore, regulatory frameworks such as ITIL v4 and ISO standards are widely adopted to standardize service processes, with AI enhancements ensuring compliance even in autonomous workflows.
Pricing structures vary significantly across the landscape, ranging from entry-level options for mid-market platforms to premium enterprise tiers with advanced AI features. Understanding these cost structures relative to value delivery is crucial for budget planning and vendor selection.
Segmentation and Deployment Strategies
The market is segmented by deployment type, application functionality, and regional adoption. Cloud-based ITSM solutions have gained significant traction, offering the flexibility and scalability required for modern IT operations. These solutions support real-time visibility and multi-cloud management, which are essential for enterprises operating across diverse infrastructure environments. On-premises options remain relevant for organizations with specific compliance or data sovereignty requirements, though the trend favors cloud adoption for its ease of updates and integrated intelligence.
In terms of application functionality, core modules such as incident management, configuration management, asset management, and change management form the backbone of ITSM operations. Incident management remains a primary focus, as rapid resolution is key to maintaining business continuity. Configuration and asset management are critical for maintaining an accurate view of the IT environment, while change management ensures that updates and modifications are executed with minimal risk. Additional functional areas continue to evolve, supporting specialized needs within the broader service management framework.
Regional dynamics also play a role in market adoption, with North America leading in market size, followed by Europe and Asia Pacific. Latin America and the Mideast and Africa represent emerging growth areas. Each region presents unique challenges and opportunities regarding regulatory compliance, infrastructure readiness, and vendor presence. Our report details these regional nuances to help global organizations tailor their strategy accordingly.
Competitive Landscape and Strategic Positioning
The competitive landscape is characterized by a mix of established enterprise platforms and agile mid-market solutions. Market concentration is notable, with a significant share held by leading vendors. ServiceNow stands out as a leading enterprise ITSM platform, leveraging an AI-driven autonomous workforce and full ITIL-aligned service management. Recent developments include the launch of the Autonomous Workforce with AI specialists for Level 1 service desk operations and the introduction of Otto as a unified enterprise AI experience. These innovations expand the capabilities for governed autonomous work across systems, setting a high bar for enterprise competitors.
BMC offers BMC Helix ITSM, focusing on AI-enabled proactive service management, change management, and multi-cloud capabilities. Atlassian provides Jira Service Management, which integrates DevOps and unified IT operations within the Atlassian ecosystem, recently releasing updates with portal improvements and asset management enhancements. Ivanti delivers Ivanti Neurons for ITSM, featuring a modern UI, agentic AI, and workflow automation for proactive service delivery, with recent releases enhancing conversational AI frameworks and system-wide summarization.
Freshworks provides Freshservice, an AI-powered ITSM platform tailored for the mid-market with quick deployment and AI assistance. ManageEngine offers ServiceDesk Plus, a unified platform with AI assistant capabilities for SMB and enterprise IT service management. Microsoft integrates ITSM capabilities with Microsoft 365 and Dynamics for seamless enterprise service delivery. Broadcom maintains CA Service Desk Manager for proactive IT service management and automation. Honeywell utilizes ServiceNow-powered ITSM solutions for enterprise-scale operations and compliance in industrial and manufacturing sectors.
Each vendor brings a distinct value proposition, and the choice often depends on existing ecosystem investments, scale requirements, and specific functional needs. Understanding the strengths and recent moves of these key players is vital for making informed procurement decisions.
Comprehensive Report Coverage
This market research report offers an exhaustive analysis of the ITSM software market, designed to equip stakeholders with actionable intelligence. The contents include detailed historical data and forecast figures, enabling precise planning and budgeting. The report dissects the market by type, application, and region, providing clarity on where growth is concentrated without merely listing superficial statistics.
Competitive profiling is a core component, with deep dives into the product offerings, strategic positioning, and recent developments of key market participants. We analyze recent product launches and feature releases to illustrate the direction of innovation. For instance, the integration of autonomous AI workforce capabilities and conversational AI frameworks represents a shift toward proactive rather than reactive service management.
Furthermore, the report contextualizes these findings within broader industry dynamics, including labor cost implications, compliance pressures, infrastructure trends, and pricing models. This holistic view ensures that readers understand not just the numbers, but the forces driving them. The analysis is structured to support strategic planning, vendor selection, and investment justification.
Strategic Implications for 2026 Decision-Makers
For decision-makers in 2026, the implications of these market trends are clear. First, the integration of AI into ITSM is no longer optional for enterprises seeking to optimize costs and improve service quality. Platforms that offer autonomous capabilities and governed workflows provide a distinct advantage in managing the increasing volume of service requests.
Second, compliance and data privacy must be central considerations in vendor selection. With the surge in data subject requests, platforms that offer audit-ready features and robust governance are essential for mitigating risk. Third, the shift toward cloud-based deployment enables greater agility and scalability, aligning ITSM capabilities with modern infrastructure strategies.
IT Service Management (ITSM) Software Market
Finally, understanding the competitive landscape helps organizations avoid vendor lock-in and negotiate better terms. Knowing the strengths of each major player allows for a more tailored fit between organizational needs and platform capabilities. This report serves as a guide to navigate these complexities, ensuring that technology investments align with broader business objectives.
Conclusion
The ITSM software market is poised for continued growth and innovation, driven by technological advancements and evolving operational demands. Organizations that proactively assess their service management strategies and adopt platforms aligned with future trends will be better positioned to succeed. This report provides the comprehensive intelligence needed to make those strategic decisions with confidence. Access the full analysis to gain deep insights into market size, segmentation nuances, competitive dynamics, and actionable recommendations for navigating the ITSM landscape through 2032.
For detailed analysis of this topic, please visit the official page: IT Service Management (ITSM) Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dental Drug Market to Reach $6.8B by 2032, 6.2% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Dental Drug Market: Strategic Intelligence for 2026 and Beyond
Executive Summary: The Imperative for Precision Intelligence
The dental pharmaceutical sector is undergoing a structural transformation. For executives, investors, and market strategists, relying on generic healthcare forecasts is no longer sufficient. The Dental Drug Market operates at the intersection of clinical necessity, specialized regulatory pathways, and evolving reimbursement models. Our latest comprehensive market research report is designed to cut through the noise, providing a granular, data-backed roadmap for decision-making throughout the forecast period extending to 2032.
As we enter 2026, the market stands at a pivotal juncture. Following a trajectory of steady growth from 2020 through 2025, the industry is projected to continue its expansion, driven by rising prevalence of dental caries, periodontal diseases, and an aging population demanding restorative and pain management solutions. This research does not merely present historical snapshots; it constructs a forward-looking strategic framework. By synthesizing macroeconomic indicators with micro-level competitive intelligence, we empower stakeholders to allocate capital efficiently, identify white-space opportunities, and anticipate regulatory headwinds before they impact margin structures.
Market Trajectory and Core Growth Dynamics
Understanding the baseline momentum is critical for any strategic plan. Our analysis tracks the market's evolution from a base value of approximately 5,200 million USD in 2020, reflecting a period of recovery and stabilization post-pandemic disruptions. Through 2025, the market has demonstrated resilience, with year-over-year fluctuations reflecting supply chain adjustments and shifting clinical priorities. The current valuation for 2025 stands at 5,850 million USD, indicating a robust recovery and renewed demand for specialized dental pharmaceutical products.
Looking ahead, the forecast period from 2026 to 2032 paints a picture of sustained growth. The market is expected to reach milestone valuations in the coming years, underpinned by a Compound Annual Growth Rate of 6.2 percent. This growth rate is not merely a statistical projection; it represents the compounded effect of increasing dental visit frequencies, the integration of pharmaceutical components into broader dental workflows, and the continuous innovation in pain management and infection control. Stakeholders must recognize that this growth is uneven across categories and geographies. While the aggregate numbers suggest stability, the underlying segments tell a more complex story of divergence, where certain therapeutic classes and delivery mechanisms are outpacing others. Our report deconstructs this complexity, allowing firms to pivot their strategies toward high-velocity pockets rather than chasing legacy volume.
Therapeutic Class and Formulation Landscapes
The diversity of products within the dental drug ecosystem requires a nuanced understanding of therapeutic demand. The market is not monolithic. It spans from immediate clinical interventions to long-term preventive care. Our segmentation analysis dives deep into the performance of various therapeutic classes, revealing which categories are capturing clinician and patient attention.
Dental Market
Local anesthetics remain a cornerstone of dental practice, forming a substantial portion of the revenue mix due to the fundamental necessity of pain control during procedures. However, the landscape extends far beyond numbing agents. Antimicrobials and antiseptics play a critical role in infection management, particularly as antibiotic stewardship becomes more stringent. Anti-inflammatories and analgesics continue to see demand, influenced by both clinical efficacy and broader public health conversations around pain relief. Furthermore, preventive and maintenance categories such as fluoride and remineralization agents, desensitizing agents, and hemostatics represent essential components of modern chairside workflows. Each of these classes operates under different pricing pressures, reimbursement rules, and competitive intensities.
Parallel to therapeutic classification, the delivery mechanism is a key battleground for differentiation. The market encompasses a wide array of formulations, including topical gels and pastes, varnishes and paints, mouthrinses and oral washes, injectable solutions, local delivery systems, and systemic oral antibiotics or analgesics. The choice of formulation often dictates the procurement process, the clinical adoption curve, and the manufacturing complexity. For instance, injectable solutions and topical gels require distinct compliance protocols and supply chain capabilities. Manufacturers that can innovate across these formats, or consolidate offerings to simplify procurement for dental practices, hold a distinct advantage. Our report evaluates the relative traction of each formulation type, helping companies understand where to concentrate R&D resources and commercial efforts.
Regional Market Architecture
Geography remains a primary determinant of market potential and risk. The Dental Drug Market exhibits significant variation in maturity, regulatory environment, and purchasing power across regions. North America continues to represent the largest revenue contributor, reflecting a well-established dental infrastructure, high patient awareness, and comprehensive insurance coverage mechanisms. Europe follows as a major market, characterized by diverse national healthcare policies and a strong emphasis on public health outcomes. The Asia Pacific region presents a compelling growth narrative, driven by expanding dental care access, rising disposable incomes, and a growing middle class seeking aesthetic and restorative treatments. Latin America and the Middle East and Africa, while smaller in absolute terms, offer niche opportunities for market entry and brand building in emerging dental ecosystems.
Crucially, regional revenue splits are not static. They are influenced by currency fluctuations, localized manufacturing capabilities, and the degree of integration between dental equipment suppliers and pharmaceutical distributors. A strategy that works in the mature markets of North America may require significant adaptation for the price-sensitive, volume-driven environments found elsewhere. Our analysis provides the contextual depth needed to assess regional attractiveness without relying on one-size-fits-all assumptions.
Competitive Landscape: Who Is Shaping the Market?
The competitive environment is defined by a mix of specialized manufacturers, large diversified conglomerates, and strategic distributors. Market concentration metrics indicate that the top three players hold approximately 35 percent of the market share, while the top five account for roughly 40 percent. This concentration suggests a moderately fragmented landscape where scale matters, but innovation and niche specialization can still secure significant positions.
Sector leaders are actively reshaping their positions through strategic moves and portfolio expansions. Septodont Holding, headquartered in France, stands out as a leading manufacturer focused on local and topical anesthetics, maintaining a strong global distribution footprint. Their recent strategic investment in Balanced Pharma Inc., including a board appointment in early 2025, signals a clear intent to support the development of enhanced dental injection drugs and to influence the next generation of pain management solutions. This move highlights how incumbents are looking beyond organic growth to secure future pipelines.
Dentsply Sirona, based in the United States, integrates pharmaceutical components such as anesthetics, endodontic irrigants, and hemostatic agents directly into broader dental workflows. Their strength lies in the synergy between hardware and consumables, offering practices a unified ecosystem. Henry Schein, also US-based, operates as a major distributor and provider, leveraging an extensive catalog and distribution network to deliver dental anesthetic and pharmaceutical products to a wide client base. Their release of the Dental Supplies Catalog for 2025/2026 in mid-2025, featuring expanded anesthetic offerings, underscores the importance of catalog breadth and accessibility in driving volume.
Other key players further illustrate the diversity of competitive approaches. Ultrdent Products and 3M focus on desensitizing agents, cavity varnishes, and integrated components for restorative and oral care portfolios. Centrix Inc. and Pierrel specialize in dental anesthetics and local formulations for office-based procedures, catering to the practical needs of clinical settings. Huons Global from South Korea and Normon from Spain add geographic depth, manufacturing and distributing anesthetics and related drugs within their respective regions. Balanced Pharma Inc. represents an emerging innovator focused on developing new dental injection drugs and analgesics aimed at reducing opioid use, aligning product development with shifting societal and regulatory expectations around pain management.
Understanding the strategic intent and operational focus of these companies is essential for competitive positioning. Our report profiles these key players, analyzing their product portfolios, geographic reach, and recent activities to help clients anticipate competitor responses and identify partnership or acquisition targets.
Regulatory, Reimbursement, and Operational Headwinds
No strategic analysis of the dental drug market is complete without a rigorous examination of external forces that can alter profitability and access. The regulatory environment is tightening, with direct implications for drug development, approval timelines, and pricing structures. The FDA has published Prescription Drug User Fee Act fee rates for fiscal year 2026, with application fees for drugs requiring clinical data reaching over 4.6 million USD. Such costs raise the barrier to entry for new formulations and incentivize companies to optimize their regulatory strategies or pursue line extensions of existing approved products.
On the reimbursement front, the Medicare Drug Price Negotiation Program has begun to implement negotiated prices for selected Part D drugs starting in 2026, with additional selections announced for applicability in 2028. Medicare beneficiaries are projected to save an estimated 1.5 billion USD in 2026 from the first round of negotiated prices. While dental drugs often fall through the cracks of broad Medicare negotiations, the precedent set by these policies influences payer expectations, hospital and clinic procurement negotiations, and the broader pricing architecture across the pharmaceutical supply chain. Companies must assess how these downstream pricing pressures might eventually cascade into dental-specific channels.
Operational costs are another critical variable. Dental drug manufacturing and distribution involve specialized labor for cartridge filling, quality control, and compliance with regulatory standards in dental clinics and pharmacies. Labor costs and the availability of skilled personnel can impact production scalability and margin stability. Furthermore, the supply of active pharmaceutical ingredients remains a strategic concern. For example, local anesthetics dominate the dental drug segment, driven by API sourcing for lidocaine and related compounds. Volatility in raw material availability or pricing can disrupt supply chains and force companies to maintain higher inventory buffers or diversify sourcing strategies. Our report integrates these operational and regulatory dynamics into a cohesive risk assessment framework, enabling clients to stress-test their business models.
Inside the Report: A Toolkit for Decision Makers
The value of a market research report lies in its actionable utility. Our Dental Drug Market study is structured to serve as a practical toolkit for strategy teams, product managers, and investors. It moves beyond descriptive analytics to provide diagnostic and prescriptive insights.
- Comprehensive Market Sizing and Forecasting: Detailed baseline data and multi-year projections that allow you to benchmark your internal forecasts and align long-term planning with sector-wide trends.
- Segmentation Deep Dives: Granular analysis by region, therapeutic class, and formulation type, highlighting growth rates, revenue contributions, and demand drivers for each segment without the ambiguity of aggregated data.
- Competitive Intelligence Profiles: In-depth company profiles covering product offerings, geographic presence, recent developments, and strategic positioning, enabling you to map the competitive battlefield and identify gaps.
- Regulatory and Reimbursement Analysis: A forward-looking assessment of policy changes, fee structures, and negotiation programs that could impact pricing, market access, and compliance costs.
- Supply Chain and Cost Structure Insights: Examination of labor requirements, raw material dependencies, and manufacturing complexities, providing context for margin analysis and operational planning.
- Strategic Recommendations: Synthesized findings that translate data into actionable guidance for market entry, portfolio optimization, M&A targeting, and risk mitigation.
Strategic Outlook: Positioning for 2026 and the Decade Ahead
As the market progresses through the forecast window, success will depend on agility and precision. The companies that thrive will be those that can balance scale with specialization, navigate an increasingly complex regulatory environment, and align their product portfolios with the evolving clinical and economic priorities of dental practices. Growth will not be uniform; it will be captured by firms that understand where demand is intensifying, which therapeutic classes are gaining clinical preference, and how reimbursement shifts might alter procurement behavior.
Dental Drug Market
This is why high-quality, timely intelligence is indispensable. Our report provides the foundation for making informed decisions in 2026 and beyond. Whether you are evaluating a new product launch, assessing a potential acquisition, refining your geographic expansion plan, or simply seeking to validate your internal assumptions against external reality, this research delivers the clarity required to move with confidence. The data points, segmentation detail, and competitive assessments contained in the full study offer a level of depth that surpasses public information and equips you to anticipate rather than react.
To access the complete analysis, including all segmentation data, detailed company profiles, and proprietary strategic recommendations, we invite you to explore the full report. The Dental Drug Market holds significant promise, but realizing that promise demands more than surface-level observation. It requires a rigorous, evidence-based perspective that our research is designed to deliver.
For detailed analysis of this topic, please visit the official page: Dental Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Hydraulic Bolt Tensioner Market Hits $211.1M in 2025, Projecting 5.5% CAGR to 2032
By PW Consulting, 2026-09-16
Precision Under Pressure: Strategic Intelligence for the Hydraulic Bolt Tensioner Market 2026–2032
In an era where asset integrity, operational safety, and predictive maintenance define competitive advantage, the hydraulic bolt tensioner market stands at a critical inflection point. As heavy industry, energy infrastructure, and renewable power generation push equipment to higher reliability thresholds, controlled axial force application is no longer a technical afterthought—it is a strategic imperative. Our latest hydraulic bolt tensioner market research delivers a comprehensive, decision-ready intelligence framework designed specifically for executives, category managers, and engineering procurement leaders navigating the 2026–2032 horizon. This report bridges historical performance data with forward-looking market mechanics, offering a clear lens through which to calibrate capital allocation, supplier partnerships, and technology roadmaps.
The market has demonstrated consistent expansion over the past half-decade, reflecting a structural shift toward precision bolting solutions across both traditional energy and emerging clean-power sectors. Historical trajectories from 2020 through 2025 reveal steady revenue growth driven by infrastructure modernization, offshore operational complexity, and the industrial sector’s increasing reliance on standardized flange management. Building on this foundation, our forecast period maps a measured but resilient expansion pathway, with a five-year compound annual growth rate that underscores the market’s maturity while highlighting pockets of accelerated demand. By anchoring 2026 strategic planning in empirically validated sizing, procurement teams can move beyond speculative budgeting and align tender strategies, inventory positioning, and service-level agreements with actual consumption velocities. The research deliberately separates headline trajectory from localized execution variables, ensuring that decision-makers understand both the macro momentum and the operational levers that shape regional and application-specific procurement outcomes.
Decoding Market Architecture and Demand Drivers
Market growth is not uniform; it is engineered by intersecting technical requirements, environmental constraints, and cost optimization mandates. Our analysis dissects the structural layers that determine where demand concentrates, how product configurations diverge, and which operational variables dictate procurement timing. Across industrial ecosystems, the shift toward predictive maintenance and reduced unscheduled downtime has elevated hydraulic tensioning from a reactive repair tool to a standardized joint-integrity practice. This transition is particularly pronounced in sectors where flange leakage, bolt fatigue, or inconsistent preload directly impact safety certifications and operational continuity.
Application segmentation reveals how end-use environments shape product specification requirements and purchasing cycles. Traditional energy infrastructure continues to anchor baseline demand, while power generation and heavy industrial processing expand the addressable use case portfolio. Each vertical presents distinct procurement rhythms, technical validation criteria, and lifecycle cost considerations. For instance, offshore and subsea environments prioritize corrosion-resistant construction, seal integrity, and rapid deployment protocols, whereas onshore industrial and power generation settings often emphasize labor efficiency, repeatable tensioning cycles, and compliance documentation. The research maps these contextual differences without reducing them to static percentages, instead providing a qualitative and quantitative framework that helps procurement leaders anticipate specification drift, evaluate supplier capability matrices, and structure tender requirements that reflect actual field conditions rather than generic catalog descriptions.
Product Architecture and Engineering Divergence
The tensioner product landscape is defined by the operational environment in which controlled bolt preload must be delivered. Topside configurations remain the volume backbone of the market, serving onshore facilities, processing plants, and surface-level energy infrastructure where accessibility, tool interchangeability, and standardized flange compatibility drive purchasing decisions. These systems prioritize modular bridge designs, broad bolt-size coverage, and compatibility with common ANSI, ASME, and API standards, enabling maintenance teams to standardize tooling across multiple joint configurations while minimizing inventory fragmentation.
Subsea tensioning represents a more specialized segment, where underwater pressure, saltwater corrosion, and restricted access fundamentally alter design priorities. Components engineered for submerged applications typically incorporate high-strength stainless steel construction, composite sealing systems, and quick-release mechanisms that balance deployment speed with long-term reliability. The premium associated with these environmental safeguards reflects the heightened risk profile of offshore operations and the cost of failure in inaccessible locations. Meanwhile, wind energy applications introduce a distinct engineering challenge: foundation and tower bolting in geographically dispersed, often remote locations where simultaneous multi-point preload and compact equipment footprints are essential. Single-stage and multi-stage hydraulic configurations have evolved to meet these constraints, enabling crews to apply consistent axial force across restricted work zones while minimizing manual handling and exposure time.
Understanding these architectural divergences is critical for procurement strategy. A tensioner selected for topside refinery maintenance may underperform in wind farm commissioning, just as a subsea-rated unit may introduce unnecessary cost and logistical complexity for onshore industrial use. Our research separates these product families by functional design logic, deployment context, and maintenance cycle expectations, giving buyers a structured approach to matching tooling portfolios with actual operational profiles rather than relying on generalized product categorization.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderately concentrated supplier base, with a handful of established manufacturers holding meaningful share while a broader field of specialized and emerging players competes on engineering differentiation, regional responsiveness, and application-specific innovation. Leading-quadrant participants typically combine broad product portfolios with standardized compliance documentation, global distribution networks, and integrated pump-and-tensioner ecosystems that reduce procurement friction. These firms often anchor their positioning in repeatable quality assurance, interchangeable adapter systems, and documented preload accuracy, which resonates with buyers managing large asset portfolios and multi-site maintenance schedules.
Alongside these established players, supplementary manufacturers compete by targeting niche operational requirements, regional service coverage, or cost-optimized industrial configurations. Certain suppliers emphasize high-pressure axial force systems, pneumatic pump integration, and heavy-duty tooling for mining, steel, and continuous-process environments. Others differentiate through spring-return mechanisms, manual-return designs with overstroke prevention, or multi-stud tensioning solutions that reduce crew exposure and accelerate cycle times. These design choices are not merely technical features; they are procurement decision drivers that influence total cost of ownership, training requirements, and maintenance scheduling.
Recent industry activity reinforces the pace of capability expansion. Throughout 2025, multiple manufacturers updated technical documentation, expanded product catalogs, and published field-reliability guidance focused on load cell accuracy, pump output consistency, and subsea application performance. Independent wind-energy tooling introductions have also emerged, reflecting the sector’s ongoing need for specialized tensioning configurations suited to foundation and mast assembly environments. These developments signal a market where product refinement, documentation transparency, and application-specific troubleshooting resources are becoming competitive differentiators. For procurement leaders, this means supplier evaluation must extend beyond unit pricing to include technical support maturity, documentation currency, and the ability to adapt product recommendations to site-specific joint integrity requirements.
Regulatory, Cost, and Operational Dynamics Shaping 2026 Decisions
Market behavior is increasingly governed by the intersection of compliance expectations, material economics, and labor efficiency considerations. Standardization frameworks continue to influence product validation and acceptance criteria, with bolt evaluation protocols and yield-strength limits shaping how tensioning equipment is specified and audited. Buyers operating in regulated environments must ensure that selected tensioning systems align with documented axial force control requirements and that supplier documentation supports traceable compliance verification. This is particularly relevant for organizations managing multi-vendor maintenance programs or integrated asset-management contracts, where inconsistent tooling practices can complicate audit readiness and joint-integrity reporting.
Hydraulic Bolt Tensioner Market
Material and construction economics further differentiate cost structures across product families. Subsea and corrosion-intensive applications typically require high-strength stainless steel components and advanced sealing materials, which elevate baseline manufacturing costs relative to standard topside configurations. These material-driven cost premiums are justified by the operational risk profile of offshore and submerged environments, but they also require procurement teams to evaluate lifecycle cost rather than initial acquisition price alone. In parallel, labor exposure and cycle efficiency remain decisive factors in industrial and wind turbine maintenance contexts. Tooling designs that incorporate spring-return functionality, automatic retraction, or multi-stud capability reduce manual handling and streamline on-site workflows, which can materially affect service scheduling, crew safety metrics, and total maintenance cost over the equipment lifecycle.
For 2026 planning, these dynamics translate into a more deliberate procurement posture. Decision-makers must weigh specification fidelity against cost efficiency, evaluate whether premium configurations deliver measurable risk reduction in their actual operating environment, and determine how tooling standardization can reduce spare-parts complexity without compromising joint integrity. The market is no longer driven solely by equipment availability; it is shaped by how well procurement strategies align with compliance calendars, field labor constraints, and the long-term reliability expectations of critical infrastructure.
Report Architecture: What Decision-Makers Will Gain
This market research is structured to translate macroeconomic trajectory and competitive complexity into actionable procurement and strategy inputs. The report opens with a quantified market sizing framework that establishes baseline demand and forward growth expectations, then layers in segmentation logic that explains how product types, end-use environments, and regional operating conditions influence purchasing patterns. Rather than presenting raw splits as isolated figures, the analysis contextualizes each dimension within procurement decision-making, helping buyers understand where demand intensity concentrates and which variables justify specification adjustments.
A dedicated competitive profiling section maps the strategic posture of leading and supplementary manufacturers, highlighting portfolio breadth, engineering focus areas, and recent capability development activity. This enables procurement teams to benchmark supplier offerings against actual application requirements, evaluate differentiation claims with technical grounding, and construct vendor shortlists that reflect operational fit rather than marketing positioning alone. The report also includes a structured examination of market drivers, constraints, and dynamic cost factors, linking regulatory expectations, material considerations, and labor efficiency trends to purchasing and inventory strategy.
To support practical execution, the research integrates application-specific tensioning considerations, product-configuration guidance, and field-reliability themes that help operations and maintenance leaders align tooling selection with joint-integrity objectives. The output is designed for cross-functional use: strategic planning teams can leverage the growth trajectory and concentration insights for market-entry or investment assessment, procurement can use segmentation and supplier profiling to structure tenders and evaluate total cost of ownership, and engineering teams can reference the technical dynamics to validate specification choices against operational constraints. All detailed quantitative matrices, proprietary forecasting breakdowns, and deep-dive supplier benchmarks are reserved for the full report, ensuring that executive readers receive the strategic frame while retaining a clear path to complete, decision-grade intelligence.
Why 2026 Demands a More Disciplined Procurement Posture
As the hydraulic bolt tensioner market moves further into its forecast cycle, the margin for reactive purchasing continues to narrow. Demand growth is being shaped by a combination of infrastructure maturation, specialized offshore and wind-energy requirements, and the industrial sector’s ongoing push toward standardized, repeatable bolting practices. In this environment, organizations that approach procurement with a clear understanding of product architecture, supplier differentiation, and compliance-linked specification requirements will be better positioned to control total cost, reduce joint-integrity risk, and maintain operational continuity across maintenance cycles.
Industrial Belt Tensioner Market
This research provides the structural intelligence needed to make those decisions with confidence. By separating headline market momentum from the operational realities that govern specification, sourcing, and lifecycle cost, the report equips executives and procurement leaders with a planning framework that is both strategically oriented and execution-ready. The full study extends this foundation into detailed sizing tables, segmentation analysis, competitive benchmarking, and scenario-based procurement guidance—offering the depth required to convert market insight into precise 2026 action.
For detailed analysis of this topic, please visit the official page: Hydraulic Bolt Tensioner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
A motorcycle or scooter is more than just a means of transportation for many people. It can be an important part of daily commuting, family life, and personal mobility. When relocating from Noida to another city, taking the bike along may become an essential part of the moving plan. However, riding a two-wheeler across a long distance may not always be practical. Professional transportation offers a convenient way to move the vehicle while allowing the owner to focus on other relocation responsibilities.
Reliable bike transport services in noida are designed to make two-wheeler relocation more organized. From arranging pickup to preparing the bike for transit and coordinating delivery, professional transport providers can manage the major stages of the process. With proper planning, customers can reduce unnecessary delays and make their vehicle relocation more manageable.
Understanding Bike Transportation in Noida
Noida is connected to several major cities through highways and transportation networks, making it a common starting point for vehicle relocation. People may need to move their bikes because of job transfers, education, family relocation, business requirements, or a change of residence.
Instead of riding the bike for hundreds of kilometres, owners can arrange transportation through a specialized service. Depending on the route and requirements, the bike can be collected from the agreed pickup point and transported toward the destination.
When selecting bike transport in noida , customers should focus on the complete service process rather than considering only the quoted price. Details such as packing, loading, transportation, delivery, documentation, and communication should be clarified before booking.
Situations When Bike Transportation Can Be Helpful
There are many circumstances in which professional bike transportation can simplify relocation.
Relocating for Work
Employees moving from Noida to another city may already have several household and professional responsibilities. Transporting the bike separately allows them to focus on settling into their new location.
Moving for Education
Students may move between cities for higher education and still need their personal two-wheeler at the new location. Professional transportation can provide a practical option for sending the vehicle.
Purchasing a Bike From Another City
A customer who purchases a motorcycle or scooter from outside Noida may require assistance getting the vehicle to their preferred location.
Family Relocation
Families shifting homes may have multiple belongings to coordinate. Arranging separate transportation for the bike can make the overall relocation schedule easier to manage.
Temporary Transfers
Some people relocate temporarily for work or other commitments. In such cases, moving the bike through a professional service may be more convenient than undertaking a long-distance ride.
Steps Involved in a Typical Bike Transportation Process
Knowing what happens during transportation can help customers prepare properly.
1. Share Transportation Details
The first step is providing information about the bike, pickup address, destination, preferred date, and contact details.
2. Receive a Quotation
The transporter assesses the requirements and provides an estimated transportation cost. Customers should ask whether packing, loading, transportation, unloading, and delivery are included.
3. Schedule the Pickup
Once the service is confirmed, a pickup schedule is arranged. The customer should ensure that the bike is available at the agreed location and time.
4. Inspect the Vehicle
The bike's condition can be checked before transportation. Taking photographs of the vehicle from different sides creates a useful reference.
5. Prepare and Secure the Bike
Appropriate protective materials can be used according to the transportation arrangement. The bike is then positioned and secured for movement.
6. Transport the Vehicle
The bike is transported toward the destination through the planned logistics network. Transit duration may depend on the distance, route, traffic, and other operational factors.
7. Delivery and Final Inspection
After reaching the destination, the bike is unloaded and handed over. Customers can check its condition and complete the delivery process.
How to Prepare Your Two-Wheeler
A little preparation before pickup can make the process smoother.
Start by washing the bike so that existing marks and scratches are easier to identify. Take clear photographs of the front, rear, sides, wheels, fuel tank, and other important areas.
Remove accessories and personal items that are not required for transportation. Check the vehicle documents and keep them available according to the transporter's instructions.
Customers should also discuss fuel requirements before pickup. Many transportation providers have specific guidelines regarding the amount of fuel that should remain in the tank.
If the bike has any mechanical issue, inform the transporter in advance. Providing accurate information helps the service provider plan the handling requirements appropriately.
What Determines the Transportation Price?
There is no single fixed rate for every bike shipment. The final quotation may depend on several factors.
Distance: Longer routes generally require more transportation resources.
Bike model and size: Different motorcycles and scooters can have different handling requirements.
Pickup location: Accessibility of the pickup point can influence the logistics involved.
Destination: Delivery arrangements may vary depending on the destination city's location and accessibility.
Packing requirements: Additional protective packing may affect the overall quotation.
Doorstep service: Customers requesting pickup or delivery directly at their address may have different service charges.
Customers should request a detailed quotation and clarify possible additional costs before confirming the booking.
Tips for a Smooth Bike Transportation Experience
Good planning can prevent many common issues. Customers should book the service in advance whenever possible, particularly when transportation is required around a fixed relocation date.
Keep all important contact details accessible. Confirm the pickup time, destination address, transporter information, and expected delivery timeline before the bike leaves.
It is also advisable to maintain a record of the bike's condition before handing it over. Photographs and relevant documentation can provide a clear reference.
Do not assume that every transporter follows the same process. Ask questions about packing, loading, transit, unloading, and delivery so that expectations are clear from the beginning.
How to Select a Suitable Bike Transport Provider
When comparing bike transport in noida , customers can evaluate providers using several practical factors.
Look for clear communication and transparent pricing. The company should be able to explain what its quotation covers.
Check whether the provider has experience handling different types of motorcycles and scooters. A structured transportation process is also important because multiple stages need to be coordinated.
Customers should also confirm how pickup and delivery updates are communicated. Knowing who to contact during the transportation process can provide greater convenience.
Most importantly, read the service terms carefully before confirming the booking. Understanding the responsibilities of both the customer and the transporter can help avoid confusion later.
Why Choose Carbikemovers?
Carbikemovers offers vehicle transportation solutions for customers who need to relocate their two-wheelers between cities. Its transportation approach covers important stages such as pickup coordination, vehicle handling, packing, loading, transit, unloading, and delivery.
Customers looking for bike transport in noida can discuss their route, bike details, preferred schedule, and service requirements before making a booking. This allows the transportation arrangement to be planned around the customer's relocation needs.
For people moving from Noida because of employment, education, family relocation, or other reasons, having a dedicated transportation service can make the vehicle-moving portion of the process more convenient.
A Simple Checklist Before Booking
Before confirming your bike transportation, make sure you have:
-
Confirmed the pickup address
-
Confirmed the destination address
-
Checked the transportation quotation
-
Discussed packing requirements
-
Confirmed the pickup schedule
-
Prepared necessary documents
-
Photographed the bike
-
Removed personal belongings
-
Discussed fuel requirements
-
Confirmed the expected delivery timeline
This simple checklist can help customers organize the transportation process without overlooking important details.
Conclusion
Relocating a motorcycle or scooter from Noida can become easier when the transportation process is planned in advance. Professional bike transport services in noida provide an organized alternative for people who do not want to ride their vehicle over a long distance.
From documentation and vehicle preparation to secure handling and final delivery, every stage contributes to a smooth transportation experience. Customers should compare service details, understand the quotation, confirm the schedule, and communicate their requirements clearly.
For anyone searching for dependable bike transport in noida , selecting a structured transportation provider and preparing the vehicle properly can make two-wheeler relocation more convenient and manageable.
FAQs
1. Can I transport my motorcycle from Noida to another city?
Yes. Professional two-wheeler transportation services can arrange bike movement between Noida and various cities, subject to route and service availability.
2. What should I do before handing over my bike?
Clean the bike, photograph its condition, remove personal belongings, prepare the required documents, and follow the transporter's instructions regarding fuel and vehicle preparation.
3. Does the bike need to be packed before transportation?
Packing requirements depend on the transportation arrangement. Professional transport providers can explain the appropriate protective preparation before pickup.
4. Can I get doorstep bike pickup from Noida?
Doorstep pickup may be available depending on the location, vehicle accessibility, and selected service. Confirm the pickup arrangement while booking.
5. How do I get a quotation for bike transport in Noida?
Provide the transporter with your bike model, pickup location, destination, preferred schedule, and service requirements. The provider can then prepare a quotation based on the transportation details.